
If you have ever opened a T1 file for the first time, the pile of slips can feel overwhelming. This walkthrough follows the same order a Canadian firm uses, so you always know what comes next.
Before anything else, confirm the tax year and the client's filing status. Everything downstream depends on it.
Step 1: Collect and sort the slips
Start with employment income (T4), then investment income (T5), then anything else the client received. A short habit saves hours: label each document as you receive it and note what is still missing. A short habit saves hours: label each document as you receive it and note what is still missing. A short habit saves hours: label each document as you receive it and note what is still missing. A short habit saves hours: label each document as you receive it and note what is still missing.
- T4 — employment income and source deductions
- T5 — interest, dividends and other investment income
- RRSP contribution receipts
Step 2: Enter income and deductions
Enter the numbers exactly as printed on the slip, then compare totals against the client's own records. Enter the numbers exactly as printed on the slip, then compare totals against the client's own records. Enter the numbers exactly as printed on the slip, then compare totals against the client's own records. Enter the numbers exactly as printed on the slip, then compare totals against the client's own records. Enter the numbers exactly as printed on the slip, then compare totals against the client's own records. Enter the numbers exactly as printed on the slip, then compare totals against the client's own records.
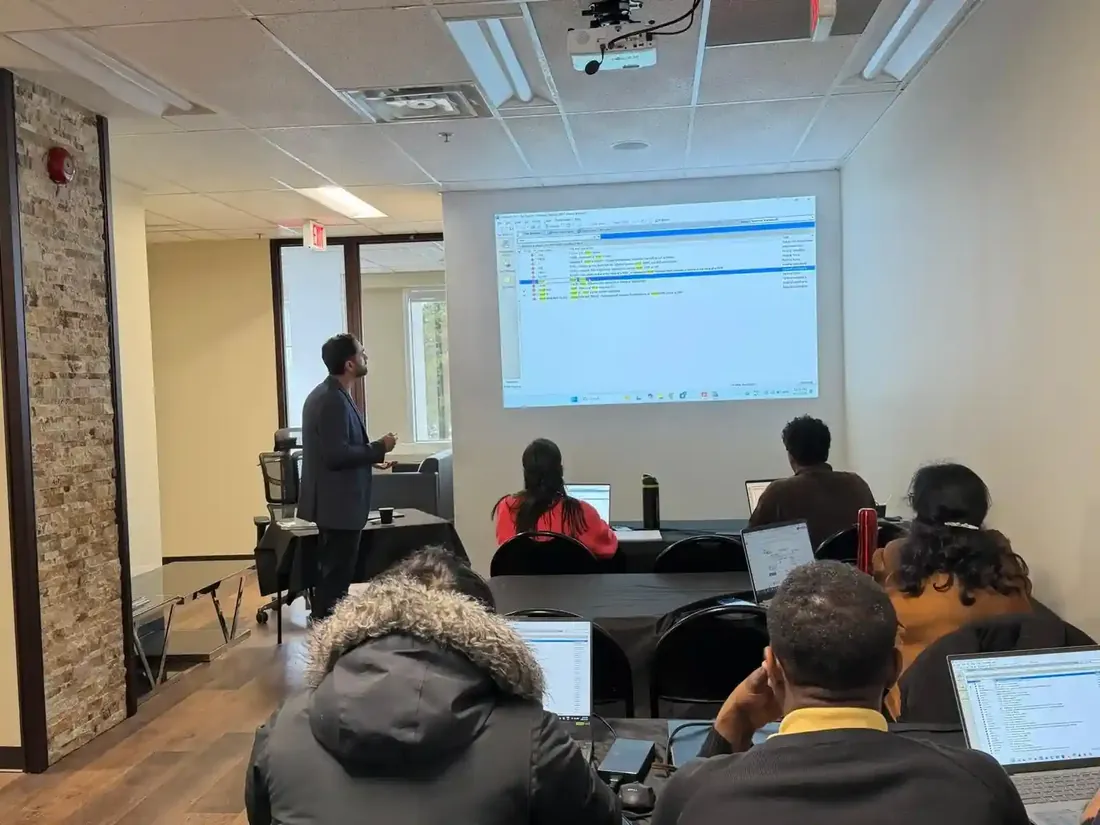
The mistakes happen in training, not later with an employer.
Step 3: Credits and claims
Non-refundable credits reduce the tax payable, but only if the supporting documents are on file. Non-refundable credits reduce the tax payable, but only if the supporting documents are on file. Non-refundable credits reduce the tax payable, but only if the supporting documents are on file. Non-refundable credits reduce the tax payable, but only if the supporting documents are on file. Non-refundable credits reduce the tax payable, but only if the supporting documents are on file. Non-refundable credits reduce the tax payable, but only if the supporting documents are on file.
| Slip | What it reports | Where it goes |
|---|---|---|
| T4 | Employment income | Line 10100 |
| T5 | Investment income | Lines 12000–12100 |
Step 4: Review before filing
A second pair of eyes catches what the preparer no longer sees. That is why every file in our co-op is reviewed. A second pair of eyes catches what the preparer no longer sees. That is why every file in our co-op is reviewed. A second pair of eyes catches what the preparer no longer sees. That is why every file in our co-op is reviewed. A second pair of eyes catches what the preparer no longer sees. That is why every file in our co-op is reviewed. A second pair of eyes catches what the preparer no longer sees. That is why every file in our co-op is reviewed. A second pair of eyes catches what the preparer no longer sees. That is why every file in our co-op is reviewed.
- Check the slips against the return
- Check the credits against the documents
- Check the totals against last year